
Ownership
Pre-purchase and insurance survey scope
| Pre-purchase | Insurance or condition | |
|---|---|---|
| Written for | The buyer | The underwriter |
| Emphasis | Defects, cost to rectify, negotiating leverage | Condition, insurability, risk of loss |
| Valuation | Usually included, often as market value | Usually required, and the basis matters |
| Sea trial | Commonly included | Often not required |
| Machinery depth | Buyer often commissions a separate engine survey | Visual inspection usually sufficient |
| Recommendations | Advice to the buyer | Frequently become conditions of cover |
| Who holds it | The buyer | Shared with the insurer |
Survey timing when buying a boat
- Agree the purchase subject to survey, with a stated period to complete it.
- Book a surveyor independent of the seller and the broker, and say the report must serve insurance as well as purchase.
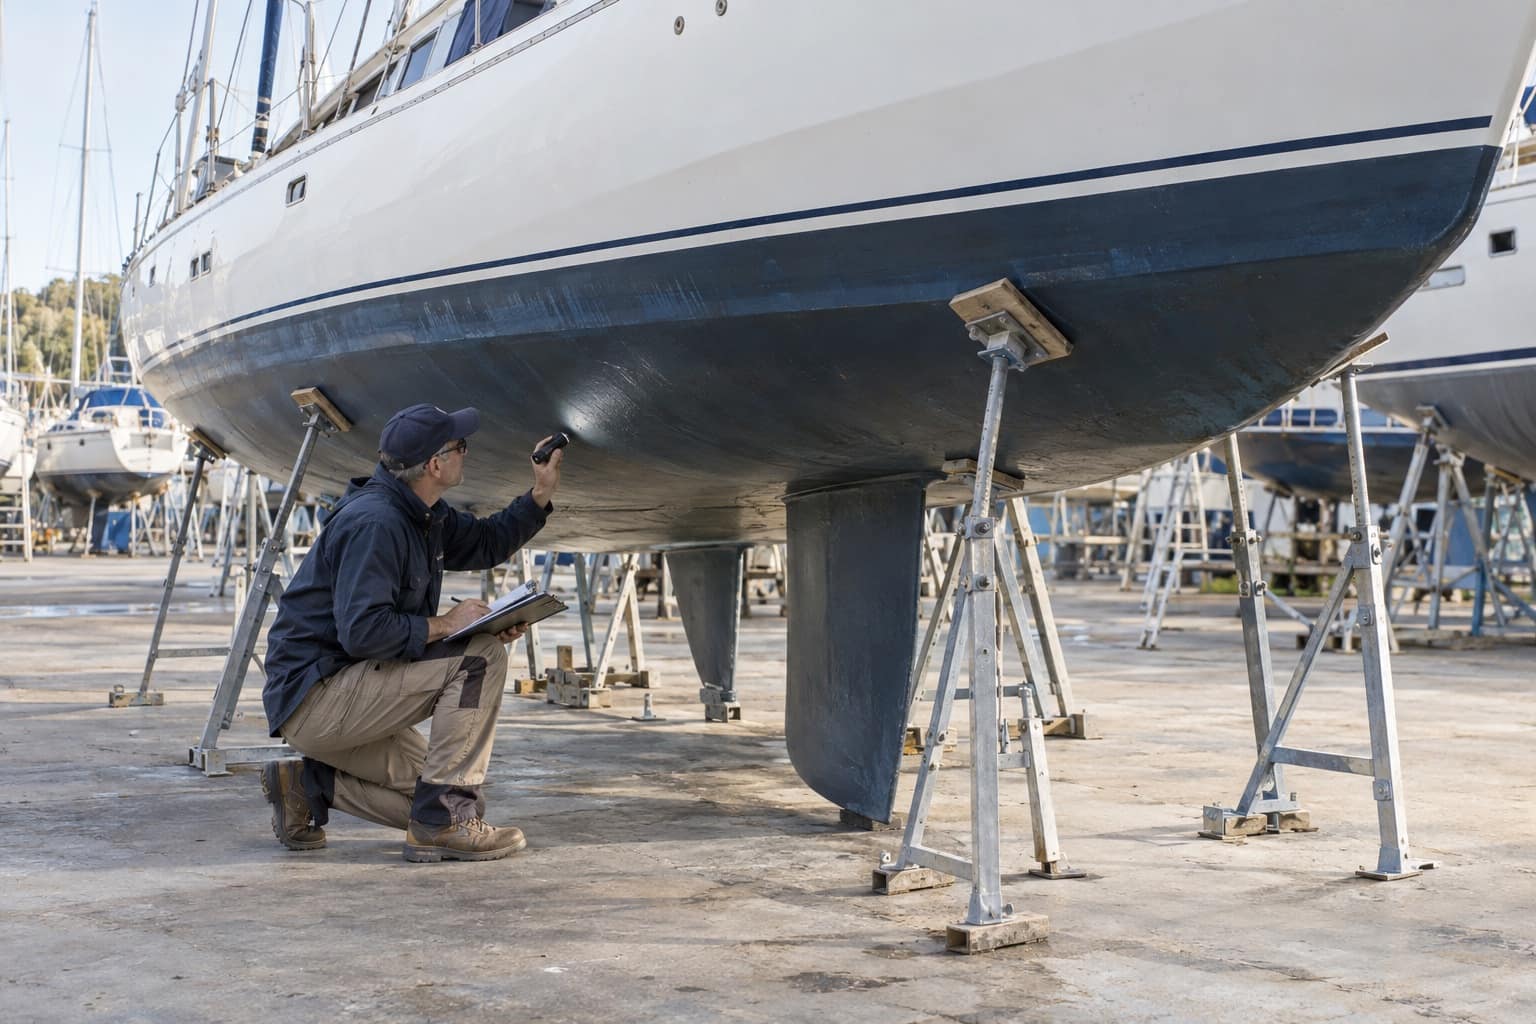
- Arrange the haul-out and attend if you can.
- Use the findings to renegotiate, rectify or withdraw.
- Send the report to insurers when quoting, and ask which recommendations they will require.
- Have cover confirmed to incept when risk passes under the contract.
When insurers require a new survey
- The report is older than the insurer's stated maximum age for the vessel.
- Significant work has been done since — a repower, a new rig, structural repair.
- The vessel has been damaged and repaired.
- You are moving to an agreed-value basis and need a current valuation.
- The vessel has crossed an age threshold that triggers a re-survey requirement.
Understanding survey findings
Read the recommendations before the narrative. The graded list is what you will act on, what you will negotiate with, and what the insurer will hold you to. Then read the valuation section and check the reasoning — which comparables, what adjustments — because that reasoning is what supports your sum insured if it is ever tested.
Condition is what decides marine claims
Almost every declined marine claim is an argument that a failure was gradual rather than sudden. The records you keep are what answers it.
Related guides
- Marine Surveys and Boat Insurance Australia
- Buying a Used Boat: Insurance Australia
- Can You Get Boat Insurance Without a Survey?
- Agreed Value vs Market Value Boat Insurance
- How To/Buying And Selling
- How To/Survey And Older Boats
- Boat Insurance Underwriting: Surveys, Age and Maintenance
General information onlyThe information on sailboatinsurance.com.au is general educational information only. It may be wrong, incomplete or out of date, and you should not rely on it as a substitute for the current policy documents or professional advice. It does not take into account your objectives, financial situation or needs and is not personal financial product advice. Insurance cover depends on the actual policy wording, Product Disclosure Statement, certificate of insurance, endorsements, exclusions, limits, sub-limits and underwriting decisions that apply to your vessel. Always read the current policy documents before buying, renewing or changing cover. For legal, financial or insurance advice about your own circumstances, consider speaking with an appropriately licensed professional.