
Ownership
Rigging age and underwriting
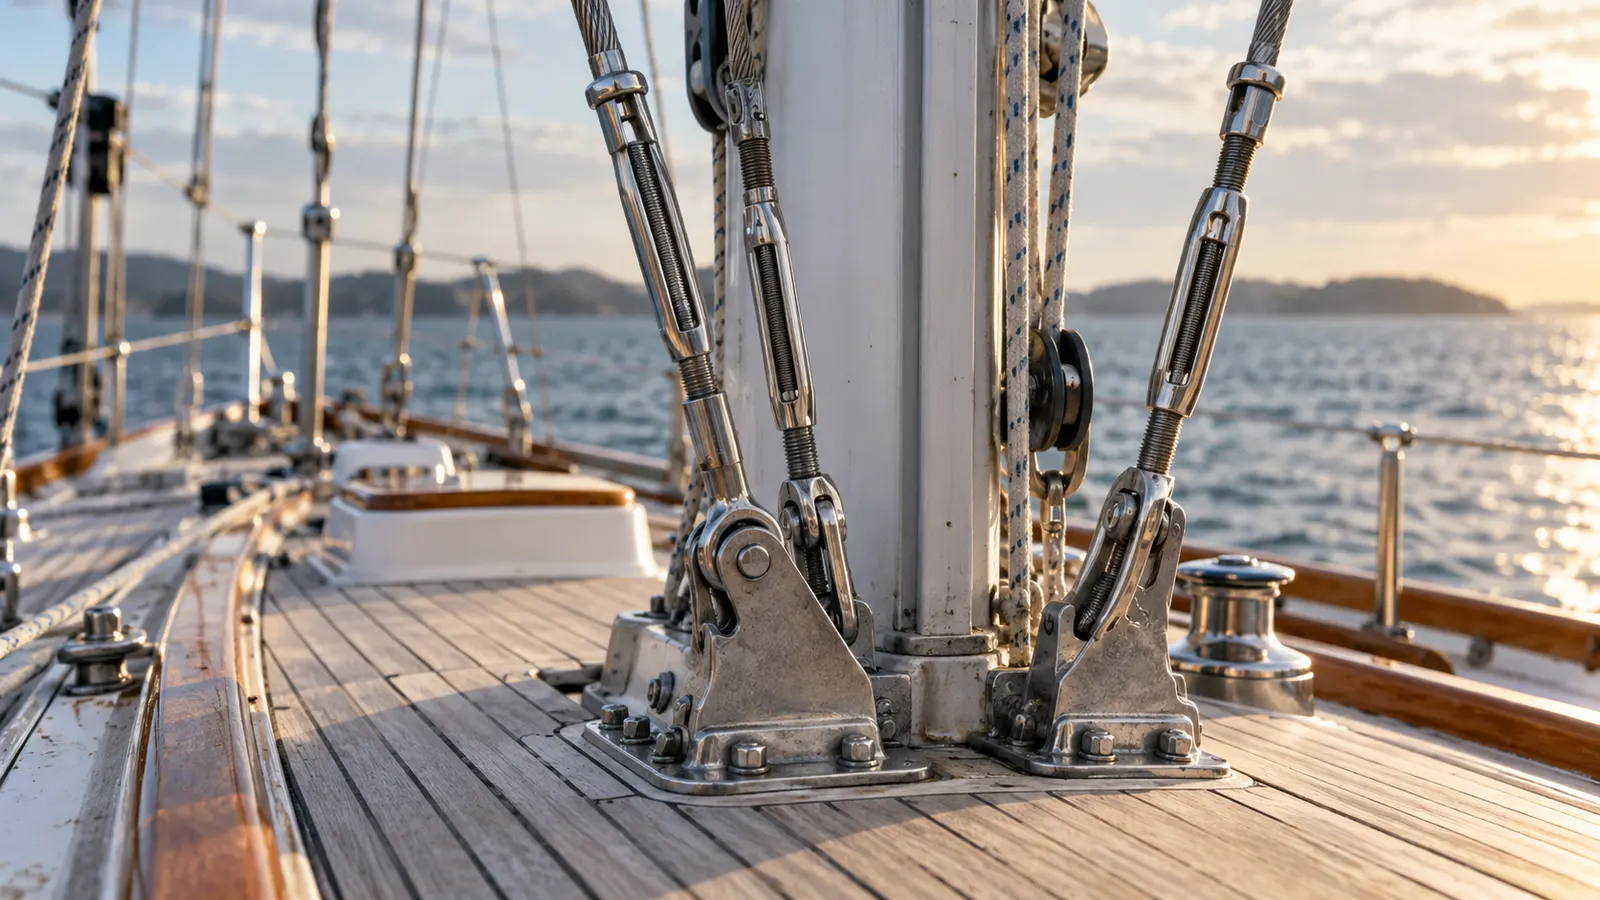
Standing rigging fails progressively and largely invisibly. Wire and terminals fatigue under cyclic loading, and the failure mode is sudden — a rig comes down, often taking sails, deck hardware and sometimes the boom with it, and occasionally injuring someone. It is a high-severity, difficult-to-inspect risk, which is exactly the profile insurers write conditions around.
Rigging replacement conditions
- A stated maximum age for standing rigging, beyond which cover is conditioned or declined
- A requirement to re-rig by a specified date as a condition of cover
- A requirement for professional rig inspection at set intervals
- An exclusion for rig-related claims where the rigging exceeds the stated age
- A higher excess applying specifically to rig claims
Checking rigging age records
- Establish when the rig was last replaced, in writing if possible.
- If no record exists, assume it is original until proven otherwise — insurers will.
- Get a professional rig inspection and keep the report.
- Check your current certificate for any rigging condition and its deadline.
- If a re-rig is required, get quotes early; rigging work books out seasonally.
Re-rigging costs and insurance terms
A re-rig is a significant expense, and owners understandably weigh it against the premium difference. That comparison undersells it. A re-rig removes a decline reason, removes a condition that could void a rig claim, and removes the possibility of losing the mast at sea. The insurance saving is the smallest of those three benefits.
A declined risk usually needs presenting, not resubmitting
Applying to a second direct insurer with the same information generally produces the same answer. Assemble the survey, history and documentation first — the checklist covers what a market will want to see.
Frequently asked questions
How old can standing rigging be before insurers object?
It varies by insurer and is set in your policy documents. Because there is no universal threshold, the only reliable answer is the one in your own wording or on your certificate.
Does an inspection substitute for a re-rig?
Sometimes. Some insurers accept a professional rig inspection in place of, or as a way of deferring, a re-rig. Whether yours does is a question for the insurer, in writing.
Related guides
- Sailing Yacht Insurance Australia
- Insuring a Boat Over 30 Years Old in Australia
- Boat Insurance Declined: Why It Happens and What to Do Next
- Bavaria Yacht Insurance in Australia
- Boat Insurance Exclusions Explained
- Pre-Purchase Survey vs Insurance Survey
- Boat Insurance Underwriting: Surveys, Age and Maintenance
- Catamaran Rig Replacement and Insurance